2025 Open Enrollment Checklist
August 2, 2024
2025 Open Enrollment Checklist

To get ready for open enrollment, employers who sponsor group health plans should be aware of compliance changes affecting the design and administration of their health plans for plan years beginning on or after Jan. 1, 2025. These changes include limits that are adjusted for inflation each year, such as the Affordable Care Act’s (ACA) affordability percentage and cost-sharing limits for high deductible health plans (HDHPs). Employers should review their health plan’s design to confirm that it has been updated, as necessary, for these changes.


In addition, any changes to a health plan’s benefits for the 2025 plan year should be communicated to plan participants through an updated summary plan description (SPD) or a summary of material modifications (SMM).


Health plan sponsors should also confirm that their open enrollment materials contain certain required participant notices, such as the summary of benefits and coverage (SBC), when applicable. Some participant notices must also be provided annually or upon initial enrollment. To minimize costs and streamline administration, employers should consider including these notices in their open enrollment materials.


Plan Design Changes

ACA Affordability Standard

The ACA requires ALEs to offer affordable, minimum-value health coverage to their full-time employees (and dependents) or risk paying a penalty to the IRS. This employer mandate is also known as the “pay-or-play” rules. An ALE is an employer with at least 50 full-time employees, including full-time equivalent employees, during the preceding calendar year.


An ALE’s health coverage is considered affordable if the employee’s required contribution for the lowest cost self-only coverage that provides minimum value does not exceed 9.5% (as adjusted) of the employee’s household income for the taxable year. For plan years beginning in 2024, the adjusted affordability percentage is 8.39%.


The affordability percentage for plan years beginning on or after Jan. 1, 2025, has not been released yet. Going forward, ALEs should take the following steps:


  • Monitor future developments for the IRS’ release of the affordability percentage for 2025; and
  • Once the affordability percentage is released, confirm that at least one of the health plans offered to full-time employees satisfies the ACA’s affordability standard. Because an employer generally will not know an employee’s household income, the IRS has provided three optional safe harbors that ALEs may use to determine affordability based on information that is available to them: the Form W-2 safe harbor, the rate-of-pay safe harbor and the federal poverty line safe harbor.


Out-of-Pocket Maximum Limits

Non-grandfathered health plans and health insurance issuers are subject to limits on cost sharing for essential health benefits (EHB). EHBs reflect the scope of benefits covered by a typical employer plan and must include items and services in 10 general categories, including emergency services, hospitalization, ambulatory patient services, prescription drugs, pregnancy, maternity and newborn care, mental health and substance use disorder services, rehabilitative and habilitative services, laboratory services, preventive and wellness services and chronic disease management, and pediatric services.


The annual limits on total enrollee cost sharing for EHB for plan years beginning on or after Jan. 1, 2025, are $9,200 for self-only coverage and $18,400 for family coverage. With this in mind, employers should take the following steps:


  • Review the out-of-pocket maximum limits for the health plan to ensure they comply with the ACA’s limits for the 2025 plan year; and
  • Keep in mind that the out-of-pocket maximum limits for HDHPs compatible with HSAs must be lower than the ACA’s limits. For the 2025 plan year, the out-of-pocket maximum limits for HDHPs are $8,300 for self-only coverage and $16,600 for family coverage.


Preventive Care Benefits

The ACA requires non-grandfathered health plans and issuers to cover a set of recommended preventive services without imposing cost-sharing requirements, such as deductibles, copayments or coinsurance, when the services are provided by in-network providers. The recommended preventive care services covered by these requirements are:


  • Evidence-based items or services with an A or B rating in recommendations of the U.S. Preventive Services Task Force;
  • Immunizations recommended by the Advisory Committee on Immunization Practices for routine use in children, adolescents and adults;
  • Evidence-informed preventive care and screenings in guidelines supported by the Health Resources and Services Administration (HRSA) for infants, children and adolescents; and
  • Other evidence-informed preventive care and screenings in HRSA-supported guidelines for women.


Health plans and issuers are required to adjust their first-dollar coverage of preventive care services based on the latest preventive care recommendations. In general, coverage must be provided for a newly recommended preventive health service or item for plan years beginning on or after the one-year anniversary of when the recommendation was issued. For example, health plans and issuers must cover screenings for anxiety disorders in adults, including pregnant and postpartum patients, effective for plan years beginning on or after June 30, 2024 (e.g., the plan year beginning Jan. 1, 2025, for calendar-year plans). More information on the recommended preventive care services is available at www.HealthCare.gov.


Before the beginning of the 2025 plan year, employers should take the following step:


  • Confirm the health plan covers the latest recommended preventive care services without imposing any cost sharing when the care is provided by in-network providers.


Health FSA Contributions

The ACA imposes a dollar limit on employees’ pre-tax contributions to a health FSA. This limit is indexed each year for cost-of-living adjustments. An employer may set their own dollar limit on employees’ contributions to a health FSA as long as the employer’s limit does not exceed the ACA’s maximum limit in effect for the plan year. For plan years beginning in 2024, the health FSA limit is $3,200. The IRS has not yet released the health FSA limit for plan years beginning in 2025. Moving forward, employers with health FSAs should take these steps:


  • Monitor future developments for the release of the health FSA limit for 2025;
  • Once the IRS releases the health FSA limit, confirm that employees will not be allowed to make pre-tax contributions in excess of the limit for the 2025 plan year; and
  • Communicate the health FSA limit to employees as part of the open enrollment process.


HDHP and HSA Limits

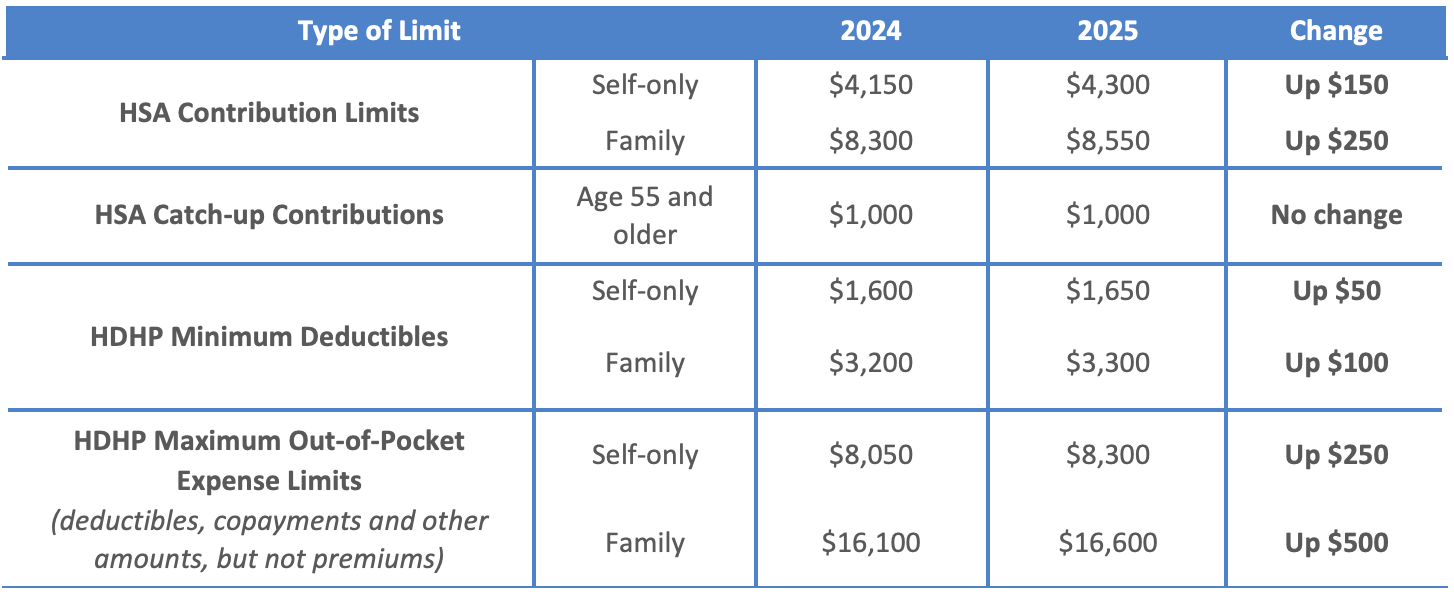
The IRS limits for HSA contributions, HDHP minimum deductibles and HDHP maximum out-of-pocket expenses all increase for 2025. The HSA contribution limits will increase effective Jan. 1, 2025, while the HDHP cost-sharing limits will increase effective for plan years beginning on or after Jan. 1, 2025. Looking ahead, employers should take these steps:


  • Check whether HDHP cost-sharing limits need to be adjusted for the 2025 limits; and
  • Communicate HSA contribution limits for 2025 to employees as part of the enrollment process.


The following table contains the HDHP and HSA limits for 2025 compared to 2024. It also includes the catch-up contribution limit that applies to HSA-eligible individuals age 55 and older, which is not adjusted for inflation and stays the same from year to year.
HDHPs: Expiration of Design Options

To be eligible for HSA contributions for a month, an individual must be covered under an HDHP as of the first day of the month and have no other impermissible coverage. In general, except for preventive care benefits, no benefits can be paid by an HDHP until the minimum annual deductible has been satisfied. However, there are a few narrow exceptions to the minimum deductible requirement, including the following exceptions that are expiring:


  • For plan years ending after Dec. 31, 2024, an HDHP is no longer permitted to provide benefits for COVID-19 testing and treatment without a deductible (or with a deductible below the minimum deductible for an HDHP); and
  • For plan years beginning on or after Jan. 1, 2025, an HDHP is no longer permitted to provide benefits for telehealth or other remote care services before plan deductibles have been met.


Due to these changes, employers with HDHPs should take these steps for plan years beginning in 2025:


  • Confirm that HDHPs will not pay benefits for COVID-19 testing and treatment before the annual minimum deductible has been met;
  • Confirm that HDHPs will not pay benefits for telehealth or other remote care services (except for preventive care benefits) before the annual minimum deductible has been met; and
  • Notify plan participants of any changes for the 2025 plan year regarding COVID-19 testing and treatment and telehealth services through an updated SPD or SMM.


EBHRA Limit

An excepted benefit health reimbursement arrangement (EBHRA) is an employer-funded health care account that reimburses employees for their eligible medical expenses on a tax-free basis. Employers can use EBHRAs to supplement their traditional group health plan coverage and help employees with their out-of-pocket medical expenses, including deductible, copayment and coinsurance amounts. Employers of all sizes may offer EBHRAs. Although an employer must offer a traditional group health plan, employees are not required to enroll in the employer’s group coverage (or any other type of coverage) to be eligible for the EBHRA.


Only employers can contribute to HRAs, including EBHRAs. EBHRAs are subject to a maximum amount that may be made newly available for the plan year. This maximum amount is adjusted annually for inflation. For 2024 plan years, the contribution limit is $2,100. This limit increases to $2,150 for plan years beginning in 2025.


Employers that sponsor EBHRAs should take the following steps:


  • Decide how much will be contributed to the EBHRA for eligible employees for the 2025 plan year, up to a maximum of $2,150; and
  • Communicate the EHBRA’s annual benefit amount to employees as part of the open enrollment process.


Mental Health Parity – Required Comparative Analysis for NQTLs

The Mental Health Parity and Addiction Equity Act (MHPAEA) requires parity between a group health plan’s medical/surgical benefits and its mental health or substance use disorder (MH/SUD) benefits. These parity requirements apply to financial requirements and treatment limits for MH/SUD benefits. In addition, any nonquantitative treatment limitations (NQTLs) placed on MH/SUD benefits must comply with MHPAEA’s parity requirements. For example, NQTLs include prior authorization, step therapy protocols, network adequacy and medical necessity criteria.


MHPAEA requires health plans and issuers to conduct comparative analyses of the NQTLs used for medical/surgical benefits compared to MH/SUD benefits. This analysis must contain a detailed, written and reasoned explanation of the specific plan terms and practices at issue and include the basis for the plan’s or issuer’s conclusion that the NQTLs comply with MHPAEA. Plans and issuers must make their comparative analyses available to specific federal agencies or applicable state authorities upon request. In recent years, the U.S. Department of Labor (DOL) has made MHPAEA compliance a top enforcement priority, with a primary focus being MHPAEA’s parity requirements for NQTLs. Considering this information, employers should take the following step:


  • Reach out to health plan issuers (or third-party administrators) to confirm that comparative analyses of NQTLs will be updated, if necessary, for the plan year beginning in 2025.


Prescription Drug Benefits – Creditable Coverage Determination

The Inflation Reduction Act of 2022 (IRA) includes several cost-reduction provisions affecting Medicare Part D plans, which may impact the creditable coverage status of employer-sponsored prescription drug coverage beginning in 2025. For example, effective for 2025, Medicare enrollees’ out-of-pocket costs for prescription drugs will be capped at $2,000.


Employers that provide prescription drug coverage to individuals who are eligible for Medicare Part D must inform these individuals and the Centers for Medicare and Medicaid Services (CMS) whether their prescription drug coverage is creditable, meaning that the employer’s prescription drug coverage is at least as good as Medicare Part D coverage. These disclosures must be provided on an annual basis and at certain other designated times, including when there is a change to a prescription drug benefit’s creditable coverage status.


Previously, CMS stated that one of the methods for determining whether coverage is creditable (the “simplified determination” method) would no longer be valid as of calendar year 2025, given the significant changes made to Medicare Part D by the IRA. However, CMS subsequently decided that it will continue to permit the use of the simplified determination methodology, without modification, for calendar year 2025 for group health plan sponsors who are not applying for the retiree drug subsidy.


Due to these developments, employers should take the following steps:


  • Confirm whether their health plans’ prescription drug coverage for 2025 is creditable or noncreditable as soon as possible to prepare to send the appropriate Medicare Part D disclosure notices; and
  • Continue to utilize the simplified determination method for determining whether prescription drug coverage is creditable for 2025, if applicable.


Open Enrollment Notices

Employers who sponsor group health plans should provide certain benefits notices in connection with their plans’ open enrollment periods. Some of these notices must be provided at open enrollment time, such as the SBC. Other notices, such as the WHCRA notice, must be distributed annually. Although these annual notices may be provided at different times throughout the year, employers often choose to include them in their open enrollment materials for administrative convenience.


In addition, employers should review their open enrollment materials to confirm that they accurately reflect the terms and cost of coverage. In general, any plan design changes for 2025 should be communicated to plan participants either through an updated SPD or an SMM.


Summary of Benefits and Coverage

The ACA requires health plans and health insurance issuers to provide an SBC to applicants and enrollees each year at open enrollment or renewal time. Federal agencies have provided a template for the SBC, which health plans and issuers are required to use. To comply with the SBC requirements, employers should include an updated SBC with open enrollment materials.


Take note that the plan administrator is responsible for providing the SBC for self-funded plans. For insured plans, the issuer usually prepares the SBC. If the issuer prepares the SBC, an employer is not required to also prepare an SBC for the health plan, although they may need to distribute the SBC prepared by the issuer.


Medicare Part D Notices

Group health plan sponsors must provide a notice of creditable or noncreditable prescription drug coverage to Medicare Part D-eligible individuals covered by, or who apply for, prescription drug coverage under the health plan. This creditable coverage notice alerts individuals about whether their prescription drug coverage is at least as good as the Medicare Part D coverage. The notice generally must be provided at various times, including when an individual enrolls in the plan and each year before Oct. 15 (when the Medicare annual open enrollment period begins). Model notices are available on the Centers for Medicare and Medicaid Services’ website.


Annual CHIP Notices

Group health plans covering residents in a state that provides a premium subsidy to low-income children and their families to help pay for employer-sponsored coverage must send an annual CHIP notice about the available assistance to all employees residing in that state. The DOL has provided a model notice. Employers should confirm they are using the most recent model notice, as the DOL updates it regularly.


Initial COBRA Notices

COBRA applies to employers with 20 or more employees who sponsor group health plans. Group health plan administrators must provide an initial COBRA notice to new participants and certain dependents within 90 days after plan coverage begins. The initial COBRA notice may be incorporated into the plan’s SPD. A model initial COBRA notice is available from the DOL.


SPDs

Plan administrators must provide an SPD to new participants within 90 days after plan coverage begins. Any changes made to the plan should be reflected in an updated SPD booklet or described to participants through an SMM. Also, an updated SPD must be furnished every five years if changes are made to SPD information or the plan is amended. Otherwise, a new SPD must be provided every 10 years.


Notices of Patient Protections

Under the ACA, group health plans and issuers that require the designation of a participating primary care provider must permit each participant, beneficiary and enrollee to designate any available participating primary care provider (including a pediatrician for children). Additionally, plans and issuers that provide obstetrical/gynecological care and require a designation of a participating primary care provider may not require preauthorization or referral for such care. If a health plan requires participants to designate a participating primary care provider, the plan or issuer must provide a notice of these patient protections whenever the SPD or similar description of benefits is provided to a participant. If an employer’s plan is subject to this notice requirement, they should confirm that it is included in the plan’s open enrollment materials. This notice may be included in the plan’s SPD. Model language is available from the DOL.


Grandfathered Plan Notices

If an employer has a grandfathered plan, they should make sure to include information about the plan’s grandfathered status in plan materials describing the coverage under the plan, such as SPDs and open enrollment materials. Model language is available from the DOL.


Notices of HIPAA Special Enrollment Rights

At or before the time of enrollment, an employer’s group health plan must provide each eligible employee with a notice of their special enrollment rights under HIPAA. This notice may be included in the plan’s SPD.


HIPAA Privacy Notices

The HIPAA Privacy Rule requires covered entities (including group health plans and issuers) to provide a Notice of Privacy Practices (or Privacy Notice) to each individual who is the subject of protected health information (PHI). Health plans are required to send the Privacy Notice at certain times, including to new enrollees at the time of enrollment. Also, at least once every three years, health plans must either redistribute the Privacy Notice or notify participants that the Privacy Notice is available and explain how to obtain a copy.


Self-insured health plans must maintain and provide their own Privacy Notices. However, special rules apply for fully insured plans, where the health insurance issuer, not the plan itself, is primarily responsible for the Privacy Notice.


Special Rules for Fully Insured Plans

The sponsor of a fully insured health plan has limited responsibilities with respect to the Privacy Notice, including the following:


  • If the sponsor of a fully insured plan has access to PHI for plan administrative functions, they are required to maintain a Privacy Notice and provide the notice upon request; and
  • If the sponsor of a fully insured plan does not have access to PHI for plan administrative functions, they are not required to maintain or provide a Privacy Notice.


A plan sponsor’s access to enrollment information, summary health information and PHI that is released pursuant to a HIPAA authorization does not qualify as having access to PHI for plan administration purposes.


Model Privacy Notices are available through the U.S. Department of Health and Human Services.


WHCRA Notices

Plans and issuers must provide a notice of participants’ rights to mastectomy-related benefits under the WHCRA at the time of enrollment and on an annual basis. The DOL’s compliance assistance guide includes model language for this disclosure.


SARs

Plan administrators required to file Form 5500 must provide participants with a narrative summary of the information in Form 5500, called a summary annual report (SAR). Group health plans that are unfunded (that is, benefits are payable from the employer’s general assets and not through an insurance policy or trust) are not subject to the SAR requirement. The plan administrator generally must provide the SAR within nine months of the close of the plan year. If an extension of time to file Form 5500 is obtained, the plan administrator must furnish the SAR within two months after the close of the extension period. A model notice is available from the DOL.


Wellness Program Notices

Group health plans that include wellness programs may be required to provide certain notices regarding the program’s design. As a general rule, these notices should be provided when the wellness program is communicated to employees and before employees provide any health-related information or undergo medical examinations. These notices are required in the following situations:


  • HIPAA Wellness Program Notice—HIPAA imposes a notice requirement on health-contingent wellness programs offered under group health plans. Health-contingent wellness plans require individuals to satisfy standards related to health factors (e.g., not smoking) to obtain rewards. The notice must disclose the availability of a reasonable alternative standard to qualify for the reward (and, if applicable, the possibility of waiver of the otherwise applicable standard) in all plan materials describing the terms of a health-contingent wellness program. The DOL’s compliance assistance guide includes a model notice that can be used to satisfy this requirement.
  • Americans with Disabilities Act (ADA) Wellness Program Notice—Employers with 15 or more employees are subject to the ADA. Wellness programs that include health-related questions or medical exams must comply with the ADA’s requirements, including an employee notice requirement. Employers must give participating employees þ a notice that tells them what information will be collected as part of the wellness program, with whom it will be shared and for what purpose, as well as includes the limits on disclosure and the way information will be kept confidential. The U.S. Equal Employment Opportunity Commission has provided a sample notice to help employers comply with this ADA requirement.


ICHRA Notices

Employers may use individual coverage health reimbursement arrangements (ICHRAs) to reimburse their eligible employees for insurance policies purchased in the individual market or for Medicare premiums. Employers with ICHRAs must provide a notice to eligible participants about the ICHRA and its interaction with the ACA’s premium tax credit. In general, this notice must be provided at least 90 days before the beginning of each plan year. Employers may provide this notice at open enrollment time if it is at least 90 days prior to the beginning of the plan year. A model notice is available for employers to use to satisfy this notice requirement.


LINKS AND RESOURCES

Sign up for our newsletter.

October 14, 2026
Changing payroll or HCM providers can be a major decision for any employer, especially for small and mid-sized businesses where payroll touches nearly every employee, every pay period, and many of the systems that keep the business running. That is why a successful transition should involve more than simply moving data from one platform into another. A new system can offer better technology, stronger reporting, improved employee self-service, and more efficient workflows. But those benefits are not automatic. If an employer simply recreates the same workarounds, outdated data, and disconnected processes in a new platform, the result may look different without actually working much better. A payroll transition should be an opportunity to step back, evaluate how the business operates today, and intentionally build a better environment for the future. Start With How the Business Actually Works Before configuring a new payroll or HCM system, it is important to understand what is happening in the current environment. That means looking beyond payroll processing and examining how information moves through the organization from onboarding and timekeeping to benefits, HR administration, reporting, and eventually separation. For many growing businesses, processes develop gradually. Spreadsheets, manual approvals, and duplicate data entry may have been created to solve individual problems over time. Together, those workarounds can create unnecessary administrative work and increase the risk of errors. Before moving into a new system, employers should identify where information is being entered more than once, what still depends on manual follow-up, where managers or employees routinely get stuck, and which reports are difficult to produce. That creates a much stronger foundation than simply asking how to make the new system look like the old one. Separate What Works From What Has Simply Become Familiar One of the easiest mistakes to make during implementation is assuming that every existing process should be preserved. Familiarity does not always mean efficiency. A payroll workflow, approval structure, or reporting process may exist simply because that is how the previous system was configured. A useful question to ask is: If we were designing this process today, would we still do it this way? Some processes will absolutely make sense to keep. Others may be creating unnecessary effort because of old system limitations. The goal should not be to change everything. It should be to preserve what works while improving the areas that create friction, confusion, or risk. Clean Up the Data Before It Becomes New-System Data Payroll and HCM systems contain a significant amount of information, including employee data, tax setup, earnings and deductions, departments, locations, job information, permissions, benefits, and timekeeping rules. Over time, some of that information may become outdated, duplicated, or structured in a way that no longer reflects the business. Moving that information into a new system without reviewing it first can preserve those same issues. A thoughtful implementation should include time to validate employee records, review earning and deduction codes, confirm tax setup, evaluate organizational structures, and identify information that should be cleaned up before migration. The objective is not simply to move data successfully. It is to start the new environment with information that is as accurate, organized, and useful as possible. Payroll Should Not Be Evaluated in Isolation Payroll may be the system that processes the paycheck, but the information it relies on comes from many different parts of the business. Hiring, timekeeping, HR, benefits, retirement contributions, employee status changes, and other workforce processes all intersect with payroll. When those areas are managed independently by different vendors or disconnected systems, employers are often left responsible for making everything work together. That can create duplicate entry, manual reconciliation, inconsistent data, and more opportunities for something to fall through the cracks. A better implementation looks at the entire administrative environment, not just the payroll engine. Why the ASO Model Matters This is where an Administrative Services Organization, or ASO, model can create meaningful value for small and mid-sized employers. Traditionally, businesses often purchase payroll, HR, benefits, retirement, and commercial insurance from separate providers. Each provider may do its individual job well, but the employer is still left managing the gaps between them. Those gaps matter because these functions are highly interdependent. A new hire can affect payroll, benefits eligibility, workers’ compensation exposure, retirement participation, and HR compliance. A termination can trigger payroll changes, benefits administration, HR documentation, and additional follow-up. An ASO approach is designed to bring those functions into a more coordinated model. Instead of asking the employer to act as the connector between multiple vendors, the goal is to create greater alignment across the services that support the workforce. At Simco, that means looking at HCM technology, HR advisory, employee benefits, commercial insurance, and retirement advisory as part of one broader business environment. The value is not simply access to more services. It is creating a more connected administrative structure with fewer handoffs, clearer ownership, and better visibility. Build Around the Employee Lifecycle, Not Just the Payroll Run A well-designed HCM environment should support more than the moment payroll is processed. It should help manage the full employee lifecycle, from onboarding and timekeeping through compensation, benefits, HR administration, retirement, and offboarding. Looking at implementation through that lens often reveals opportunities that would otherwise be missed. Onboarding may still be manual. Managers may submit changes through email. Benefit information may need to be entered in multiple places. Employee data may not flow consistently between systems. These may not seem like payroll problems, but they directly affect how efficiently payroll and HR administration operate. That is why implementation conversations should include more than pay frequency and tax setup. They should also examine how employees enter the organization, how managers interact with the system, how changes are communicated, and where administrative work tends to pile up. Leave Enough Time to Build It Correctly A thoughtful assessment takes time, which is why employers should avoid waiting until the last minute to begin a payroll or HCM transition. There is a significant difference between getting a system live and building a system well. A well-planned implementation creates room to evaluate processes, validate data, configure the system, test workflows, train users, and correct issues before employees depend on it. For employers considering a January transition, beginning the conversation in the fall can provide valuable runway and allow for more deliberate decisions before year-end pressures increase. Why Simco Starts With the Blueprint At Simco, we believe implementation should begin with understanding the business, not simply collecting files. Our Simco Blueprint assessment is designed to look at how an employer is operating today before the new environment is built. We review current processes, identify what is working, uncover areas of friction, and look for opportunities to improve how the organization uses its payroll and HCM technology. That assessment also considers how payroll interacts with HR, benefits, commercial insurance, and retirement. The objective is to make sure the system supports the business as a whole rather than solving one problem while creating another. A successful transition should leave an employer with more than a new provider. It should create a stronger foundation for how the business manages its people and administrative responsibilities. A New System Should Be an Opportunity to Work Better Changing payroll or HCM providers is a significant project, but it can also be an opportunity to improve processes that may have been creating frustration for years. The key is resisting the temptation to simply recreate the old environment. Before moving data, employers should understand their current processes. Before configuring workflows, they should decide whether those workflows still make sense. Before going live, they should make sure the different pieces of their administrative environment are working together effectively. A new system should not just be a different place to do the same work. It should help make the work easier. If your organization is considering a payroll or HCM change, Simco can help you evaluate your current environment, identify opportunities for improvement, and understand what a thoughtful transition could look like. Ready to take a closer look at your current setup? Talk with the Simco team .
October 8, 2026
January is one of the most natural times for an employer to move to a new payroll or HCM provider. A new calendar year creates a clean transition point for payroll records, reporting, employee communication and internal processes. But a January go-live does not mean the work should begin in January. For employers considering a change, the most important part of the transition often happens months earlier. A successful implementation requires time to understand the current environment, make decisions about what should change, validate employee and payroll data, configure the new system, test it and prepare everyone who will use it. If a January payroll change is on your radar, here are four things worth knowing now. 1. A January switch should usually start well before January One of the biggest misconceptions about changing payroll providers is that the transition begins when the new system goes live. In reality, that is the end of the implementation process. Before the first payroll can run, there are a number of decisions and setup items that may need attention, including employee records, earnings and deductions, tax information, pay schedules, timekeeping rules, direct deposit information, security permissions, reporting requirements, integrations and other company-specific workflows. The complexity will vary from employer to employer, which is why there is no single implementation timeline that fits every organization. But if your goal is to be live at the beginning of the year, October and early November are a much better time to begin the conversation than December. Starting earlier gives both the employer and the new provider room to work carefully instead of trying to force a major system change through the busiest part of year-end. 2. Do not automatically recreate everything you have today Changing payroll providers is an opportunity to fix problems, not transfer them. It can be tempting to approach implementation by simply copying the setup in the current system into the new one. That may seem like the fastest path, but it can also carry old inefficiencies, outdated processes and bad data directly into the new platform. Before building anything, employers should take a closer look at questions such as: Which payroll processes create the most manual work? Are employees or managers struggling with any part of the system? Are there recurring corrections or data issues? Are you maintaining information in spreadsheets because the current system does not handle it well? Are timekeeping, HR, benefits and payroll working together effectively? Are there reports your team needs but struggles to produce? Have your workforce, policies or business processes changed since the system was originally implemented? A provider change should create a better operating environment, not simply give the same process a new login screen. This assessment stage is one of the reasons beginning early matters. 3. Data accuracy becomes especially important at year-end A payroll transition involves more than moving names and pay rates. Employee information, year-to-date wages, taxes, deductions and other payroll records may all play a role in making sure the old year closes correctly and the new year begins accurately. Year-end also brings important employer reporting responsibilities. Employers remain responsible for ensuring payroll tax filings and Forms W-2 are accurate and filed on time even when they use a third-party payroll provider ( IRS ). That makes data review an important part of any year-end implementation. Employers should expect to spend time verifying items such as: Employee names, addresses and Social Security numbers Federal, state and local tax setup Year-to-date payroll totals Earnings and deduction codes Benefit deductions Retirement contributions Garnishments and other recurring deductions Direct deposit information Company tax information and filing setup There may also be special year-end items such as bonuses, fringe benefits or other adjustments that need to be reflected correctly. The goal is not simply to import data. It is to make sure the information going into the new system is accurate and that responsibility for year-end versus new-year reporting is clearly understood. 4. The right implementation should include testing, training and a clear owner Technology is only one part of a payroll conversion. Someone also needs to coordinate the process. A good implementation should establish clear responsibilities, deadlines and points of contact so the employer is not left trying to manage multiple moving pieces on their own. Before going live, employers should understand: Who is overseeing the implementation? There should be someone responsible for keeping the project moving and helping coordinate questions, decisions and outstanding items. How will the system be tested? Payroll calculations, deductions, taxes, time data and other important configurations should be reviewed before the first live payroll. How will managers and employees be prepared? If employees will use a new portal, mobile app, timekeeping process or enrollment experience, communication and training should be part of the transition. What support will be available after go-live? Implementation should not end the moment the first payroll processes. Employers should know who they will contact when questions arise afterward. A well-managed transition gives an employer time to catch issues before they become payroll-day emergencies. January can be a good time to change if you give yourself enough runway For employers who are frustrated with their current provider, January can provide a natural opportunity for a fresh start. However, this decision should not be rushed simply to hit a January 1 date. The better question is: Do we have enough time to evaluate our current process, build the new environment correctly and make the transition confidently? If the answer is yes, starting the conversation now can make the next few months much more manageable. At Simco, we work with employers to look beyond the payroll system itself. We assess how payroll, HR, timekeeping, benefits and the surrounding processes fit together so the new environment is built around how the business actually operates. If you are considering a payroll or HCM change for 2027, now is the time to start mapping out what the transition would involve. A short conversation can help determine what needs to happen, what information you will need and whether a January transition makes sense for your organization. Want to talk through your January timeline? Click here .
September 21, 2026
For a long time, conversations about employee financial wellbeing started and ended with compensation. Pay people accurately, pay them on time, offer a competitive benefits package, and the employer had largely done its part. Those things are still fundamental. But the way employees experience their finances is much broader than a paycheck arriving every other Friday. A car repair does not wait until payday. A medical bill can arrive unexpectedly. Someone trying to improve their credit may not know where to begin. Another employee may be juggling everyday expenses while trying to save for a home, pay down debt or simply build a little more breathing room into their monthly budget. Employers are not expected to solve those challenges. But increasingly, they are recognizing that they can make useful resources easier to access. That shift is helping financial wellness become a more meaningful part of the overall employee experience. Financial Wellness Is Really About Giving Employees More Options There is no single definition of financial wellness that applies to everyone. For one employee, it may mean learning how to build a budget that actually works for their household. For another, it may mean having access to earned wages when an unexpected expense comes up before payday. Someone else may be focused on improving their credit, understanding financial terminology or finding an easier way to complete an employment or income verification. That is part of what makes this area different from many traditional benefits. Employees are not all trying to solve the same problem at the same time. A strong financial wellness approach does not assume that they are. Instead, it gives employees access to a range of resources and allows them to decide what is useful for their own circumstances. The employer is not stepping into the role of financial adviser. The employer is simply making it easier for employees to find tools, education and support when they need them. That can be a powerful distinction. The Employee Experience Extends Beyond What Happens at Work When organizations think about employee experience, the conversation often centers on things like company culture, managers, career development, recognition and benefits. Those things matter enormously. But employees also bring the realities of everyday life with them when they come to work. Financial concerns are one of those realities. An employee who is worried about an unexpected expense, trying to make sense of debt or unsure where to find reliable financial information may still show up and do their job well. But that does not mean those concerns disappear during the workday. This is where employers have an opportunity to think more broadly about support. The goal is not to remove every source of financial stress. That would be unrealistic. The opportunity is to make certain situations a little easier to navigate by connecting employees with resources they may not otherwise know about or have convenient access to. Sometimes that means education. Sometimes it means greater flexibility. Sometimes it simply means removing friction from an everyday process. Taken together, those small improvements can contribute to an employee experience that feels more thoughtful and supportive. Useful Benefits Are Often the Ones Employees Can Actually Use Employers spend significant time and money building benefits packages, but a benefit only creates value when employees understand it and can realistically access it. That is one reason financial wellness resources are particularly interesting. Many of them are designed around practical, everyday needs rather than something an employee may only use once or twice a year. They can help people answer questions, learn something new, access information or manage an immediate financial need. This creates an opportunity for employers to think beyond simply adding more benefits. Sometimes the better question is: How can we make the resources already available to employees more useful, accessible and relevant to their daily lives? That mindset can be especially valuable for organizations that want to improve the employee experience without adding another complicated program for HR to administer. The Payroll and HCM Experience Is Changing Too Payroll technology has traditionally been viewed as operational infrastructure. It calculates pay, handles taxes, stores employee information and keeps the organization moving. All of that remains essential. But modern HCM platforms increasingly sit at the center of much more of the employee experience. Employees may log into the same system to view a paystub, update personal information, enroll in benefits, request time off or access other workplace resources. Because they are already interacting with that technology, it creates a natural place to connect them with additional tools. That matters. A resource hidden on an intranet page that no one remembers exists has limited value. A resource that is connected to technology employees already use has a much better chance of becoming part of their normal experience. For HR teams, there is another benefit: introducing additional employee resources does not necessarily have to mean introducing another disconnected system, another login or another administrative burden. When tools work within the broader HCM ecosystem, employers can expand what they offer while keeping the experience simpler for everyone involved. Financial Wellness Can Support the Employer, Too The most important reason to offer financial wellness resources is the value they can provide to employees. But there is an employer benefit as well. Organizations are continually looking for meaningful ways to strengthen their employee value proposition. Compensation will always be a major part of that equation, but employees also notice how easy or difficult it is to navigate everyday life at work. Can they find the information they need? Are useful resources clearly communicated? Does the technology make things easier? Does their employer seem to think about the employee experience beyond the minimum requirements? Those details shape how people experience an organization. Financial wellness resources can become one more way for employers to demonstrate that support in a practical way. They can complement existing benefits, help employees get more value from the technology already in place and give HR teams another resource to point employees toward when appropriate. The value is not necessarily in one dramatic program. Often, it is the accumulation of small conveniences and helpful resources that makes an employee experience feel noticeably better. A New Set of Resources for Simco Clients This thinking is part of why we were excited to recently expand the resources available to Simco clients through our partnership with isolved. Through isolved People Cloud™, eligible employees now have access to additional tools from FinFit, ZayZoon and Equifax , each designed to support a different part of the financial wellness and employee experience. FinFit provides financial education and wellness resources that can help employees build knowledge and confidence around everyday financial decisions. ZayZoon offers employees additional financial flexibility, including access to earned wages before the traditional payday when needed. Equifax provides employment and income verification services that can help simplify a process employees may encounter when applying for a loan, renting a home or completing other important financial transactions. Each resource serves a different purpose, and not every employee will need every tool. That is exactly the point. The goal is to create more options and make them easier to access. Making Resources Available Is Only the First Step One of the easiest mistakes employers can make is assuming that introducing a new benefit automatically means employees will use it. Usually, awareness has to come first. Employees need to know what a resource is, why it exists and when they might consider using it. That communication does not have to be complicated. A short reminder in an employee newsletter, a mention during onboarding, a benefits communication or an occasional educational email can go a long way toward keeping useful resources visible. It can also help to communicate these tools in terms employees actually relate to. Instead of simply saying, “We offer a financial wellness program,” explain what that could mean in real life: Need help understanding your budget? There is a resource for that. Want to learn more about credit? There is a resource for that. Need access to part of your earned pay before payday? There may be an option available. Completing an income verification? That process may already be easier than you think. When employees understand the practical purpose behind a resource, it becomes much more meaningful. A Better Employee Experience Is Often Built in Small Ways Supporting employees does not always require launching a major new initiative. Sometimes it means looking at the systems, benefits and resources already surrounding employees and asking whether they could be doing more. Could something be easier to access? Could employees have more flexibility? Could a process require fewer steps? Could a resource help someone feel more informed or confident? Those may seem like small questions, but they are increasingly important ones. Financial wellness is ultimately about giving employees more tools to navigate their own financial lives. Employers do not need to have every answer, and they do not need to solve every challenge. But they can help create an environment where useful resources are easier to find, easier to understand and available when they matter. For Simco, that is what makes these new resources exciting. They are not simply additional features inside a platform. They are another way the technology our clients already use can create a better experience for the people behind every payroll.  Want to learn more about the financial wellness resources now available through Simco and isolved? Contact our team to learn more.

Have a question? Get in touch.